Skip to content
Free to read · 14 chaptersAfter a death · England & Wales

The Handover Guide

Fourteen short chapters on what a family actually meets after a death — in the order the moments arrive, each one ending with what it does not cover. No account, no email, no purchase.

33-page PDF · England & Wales, with Scotland and Northern Ireland flagged where they differ · Guidance only, not legal advice

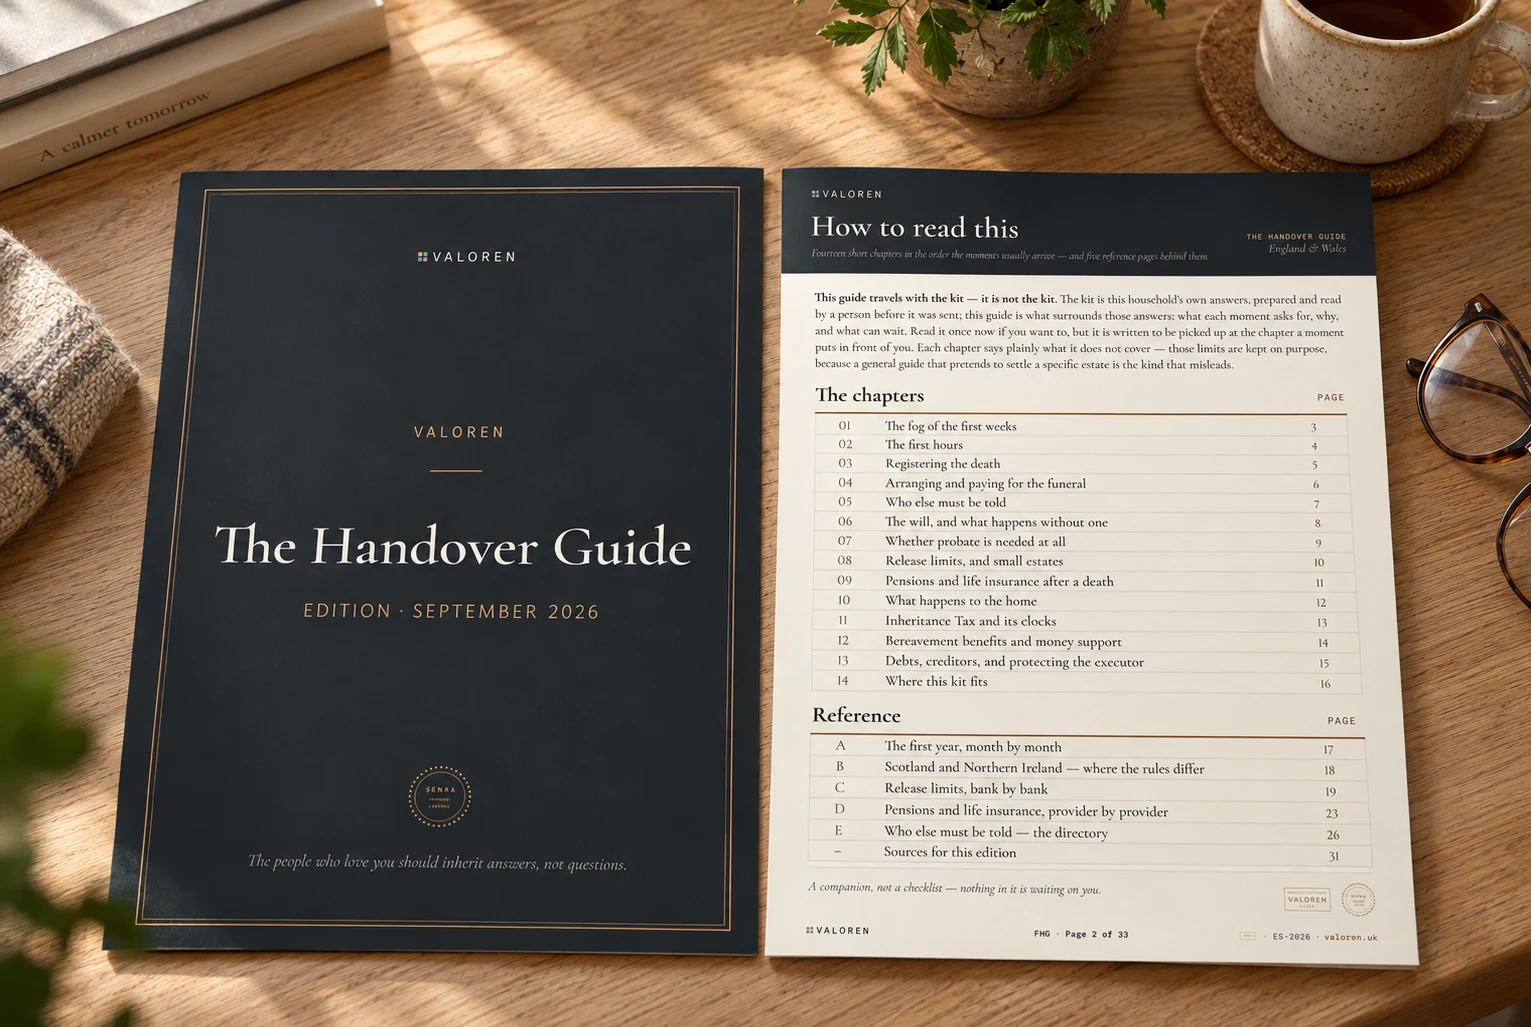
The Handover Guide's cover and its 'How to read this' page, as loose printed sheets on a wooden table beside a mug of tea and reading glasses — the real chapter list, not a bound book.

The actual guide, printed at home

Every chapter title, exactly as the free PDF prints it.

Free · no account

Guidance only. Fees, thresholds and statutory windows change, and this guide describes the procedure in England and Wales. Verify current figures at gov.uk and hmrc.gov.uk. An estate with foreign assets, trusts, a business interest or a disputed will needs professional advice, not a general guide.

This is written to be picked up at the chapter a moment puts in front of you. You do not have to read it in order, and you do not have to read it now.

Each chapter says plainly what it does not cover — those limits are kept on purpose, because a general guide that pretends to settle a specific estate is the kind that misleads.

I

The first days

The week that is mostly procedural — and how little of it is actually urgent.

Contents
01

The fog of the first weeks

The first week is mostly procedural: the medical certification of the death, then registering it — normally within five days of the medical examiner’s office confirming registration can proceed — collecting certificates, and telling the immediate family. Wider notifications, to banks, employers, insurers, friends, can wait; none of it needs to happen today, and most of it spreads across days rather than landing at once.

One named person can carry the sequence of calls; nobody else needs to hold the whole list in their head at the same time.

Treating every task as equally urgent in the first days is how families exhaust themselves before the slower work — probate, accounts, distribution — has even started. The procedural week is short; the administration behind it runs for months.

Letting one named person carry the early sequence, while everyone else waits to be told what is needed, keeps the load from landing on the whole household at once, at the point it is least able to carry it.

Almost nothing has to happen tonight, and little more has to happen this week. Grief comes in waves and rarely arrives on schedule — steady one day, gone the next, for no obvious reason. Ordinary decisions can feel harder than they should; that is common, not a sign of doing this wrong. Beyond registering the death, nothing here is waiting on you at a fixed hour. Whatever pace gets you through it is the right one.

The limit

This module describes pace, not procedure — it does not replace the day-by-day sequence in the free first-week reference, and it gives no timetable for grief itself, which has none. It is not a substitute for bereavement support, and it makes no claim about how any particular person should feel or how quickly they should recover.

In a prepared kit

The Kit's own first page states one named contact and a backup, with working phone numbers, printed as page one — Start Here. That single decision is made in advance, so nobody has to work out who calls whom while the household is still in the first hours.

Contents
02

The first hours

What happens in the first hours depends on where and how the death occurred. An expected death at home is usually verified by the GP surgery; an unexpected one means calling the emergency services, and the death may be referred to a coroner — ordinary procedure, not suspicion.

In hospital or hospice, the clinical team confirms the death. For a death not referred to the coroner, a doctor proposes the medical cause of death, the medical examiner independently reviews it, and the medical examiner’s office confirms when registration can proceed.

Nothing else is due yet.

Knowing this in advance stops the wrong things feeling urgent. Cancelling direct debits, notifying the bank, calling pension providers — none of these are time-sensitive, and several go better done in a particular order later.

The one real constraint is the medical certification: completing it — the medical examiner’s review included — is what lets registration proceed, and registration is the gate to nearly everything that follows, including Tell Us Once and probate.

Shock and disorientation are ordinary here, even where a death was expected. Some people feel a pull to act immediately, ringing round or doing something with their hands; others need only to sit with someone. Both are normal.

The limit

This module does not decide whether a coroner becomes involved — the circumstances of the death do, assessed by people qualified to make that call, not by the family. It does not describe the medical examiner's review in detail, and it is no substitute for what the attending doctor, paramedic or hospital bereavement officer says on the day.

In a prepared kit

Where the household gave them, the Kit's medical essentials carry the GP practice, regular medications and allergies in one place — the details someone would otherwise have to search for or recall from memory, at exactly the point that is hardest to do either.

Contents
03

Registering the death

Once the medical examiner’s office confirms registration can proceed, the death must normally be registered within five days in England and Wales, counting weekends and bank holidays — and where a coroner is involved, registration waits for them, with the register office saying when. Registration happens by appointment at the local register office.

The registrar provides death certificates — certified copies of the register entry, the document banks and other institutions accept — and gives a reference for Tell Us Once, a free service that reports the death to HMRC, the DWP, the DVLA, the Passport Office, the local council, Veterans UK and some public-sector pension schemes, in one step.

Registration normally unlocks the administrative steps behind it, Tell Us Once included — and where an inquest prevents registration, an interim death certificate can open a separate route. One submission genuinely saves separate calls to several government departments, which matters when grief already occupies most of a person's capacity.

But it is not everything: banks, insurers, private pensions and utilities sit outside its reach and must still be told one at a time, on each institution's own terms.

Sitting through an appointment and a form so soon after a death can feel oddly bureaucratic — a queue number in the middle of something enormous. That mismatch between the scale of the loss and the ordinariness of the process is a common, unremarkable reaction.

Scotland · Northern Ireland

Tell Us Once operates in England, Scotland and Wales; it is not available where the person who died was living in Northern Ireland, or had been living permanently abroad.

The limit

This module names what one Tell Us Once submission reaches and what it does not. It is not a walkthrough of the registrar's appointment itself, and it does not cover Scotland's different registration window, or the documents a particular register office may ask for locally, which vary by area.

In a prepared kit

The Kit's clock page carries this five-day window as one of its dated entries, printed beside this household's own first-call contact and papers location — the reminder sits with the answers it depends on, not apart from them.

Contents
04

Arranging and paying for the funeral

In England and Wales, a funeral is usually arranged — and often held — before the will is even read. Reasonable funeral expenses are payable from the estate, taking priority over ordinary unsecured debts and any distribution to beneficiaries.

Most high street banks release funds directly to the funeral director before probate is granted, on sight of the invoice and a death certificate — gated on what the account holds, not a fixed limit. Costs range from around £1,628 for a direct cremation to £5,440 for a traditional burial.

Waiting to be certain feels safer, but the funeral cannot wait for probate, and neither can the decision about who pays. A family that doesn't know the bank will move first — before any grant — either delays the funeral or pays for it personally, out of pocket, when a phone call to the bereavement team might have released the money instead.

Knowing the order of payment protects the person who acts first.

It can feel wrong to be discussing costs and providers within days of a death, while grieving. That discomfort is common — most people making funeral decisions are doing so under pressure, with little time, and often without knowing what the person would have wanted.

Scotland · Northern Ireland

Scotland runs a separate Funeral Support Payment through Social Security Scotland, operating similarly to the DWP scheme but with its own qualifying criteria and amounts.

The limit

This module does not estimate what a specific funeral will cost, confirm any bank's release limit for your household, or arrange a funeral director. It does not resolve family disagreement about what counts as a reasonable expense, and none of it is legal or financial advice — a solicitor or the bank's own bereavement team has the final word.

In a prepared kit

Where funeral wishes were given, your Kit records the preference — burial or cremation, any funeral plan provider named, where fuller wishes are kept, and what should be honoured. Its financial picture lists each bank, pension and insurer named — and beside a bank that publishes one, that bank's own release limit, with the date it was checked.

II

Telling people, and the will

Who has to be told, in what order, and what happens when there is no will.

Contents
05

Who else must be told

Tell Us Once reaches government departments and some public-sector pension schemes — it does not reach banks, private pensions, insurers or utilities. Each has to be told separately: a phone call, an online form, sometimes a signed paper form with proof of identity.

A sole-name bank account freezes the moment the bank is told; a joint account passes to the surviving holder and carries on. They commonly ask for proof of death, proof of the claimant’s identity, and whatever evidence that institution itself requires before it releases or transfers the asset.

The order protects the household as much as the paperwork does. Telling the bank before certified copies are in hand can freeze a sole account before funeral costs are paid from it, while waiting too long leaves direct debits drawing on money that should have stopped.

Above a balance threshold each bank sets for itself — one major bank publishes £50,000 — it will also want the grant of probate before releasing anything, a separate wait again.

Repeating the same explanation to organisation after organisation, sometimes to someone who has clearly done this before and sometimes to someone who hasn't, can feel exhausting in a way nobody warns you about. Irritation with the process is common and is not a judgement on the loss.

The limit

This module does not list any institution's own route, hours or document requirements — those change, and belong on that institution's own bereavement page, not a general guide. It does not settle whether probate is needed for a given household; that depends on balances and thresholds this module does not record.

In a prepared kit

The Kit's financial picture lists the banks, pensions and insurers this household named, with a release limit printed beside a bank that publishes one — and a ruled line beside each to date the day it was told, so the record of who has been informed lives with the names themselves.

Contents
06

The will, and what happens without one

A will names an executor and states who inherits. It is usually kept by the solicitor who drew it up — sometimes for decades in what solicitors call a deed box — or at home, or with a will-writing company.

Registering a will with the National Will Register is optional in the UK, so a paid nationwide search of its database of over 10.5 million records is often the first formal check, alongside asking family and searching the deceased's own papers.

Whether a valid will exists decides which form applies — probate uses PA1P, intestacy uses PA1A — and, without one, the estate passes under the intestacy rules rather than to whoever the deceased actually wanted to benefit. Even where a will exists, if the executor it names cannot or will not act, the application becomes letters of administration with the will annexed instead of a standard grant of probate.

Not knowing whether a will exists, or where to look, is an ordinary early question rather than a failure of preparation — most families start exactly here, and a clear result either way is easier to act on than uncertainty.

Scotland · Northern Ireland

Scotland's equivalent to probate is called confirmation and runs under different rules; the PA1P/PA1A forms and this module's priority-of-applicant rules are England & Wales only, though the National Will Register itself searches across the whole UK.

The limit

This module doesn't run a will search on your behalf, judge whether a particular will is valid, or say whether a cohabiting partner's dependency claim would succeed. Whether an executor can genuinely be passed over, or a will's validity is in doubt, needs a solicitor's judgement on the actual document — not a general guide.

In a prepared kit

Your Kit's legal position records where the will — or the fact there isn't one — is kept, and states which probate form follows from that: PA1P where there is a will, PA1A where there is none.

III

Probate, property and tax

Whether probate is needed at all, what each institution will release without it, and the clocks that carry a penalty.

Contents
07

Whether probate is needed at all

There is no single probate threshold — no law that says 'below this amount, you don't need it.' What decides it is what the estate holds and how it's owned. A home in the deceased's sole name almost always needs the grant regardless of value.

Jointly owned assets usually pass to the survivor without one. A sole-name bank balance depends on whether it sits above or below that particular bank's own release limit — not a single government figure.

Getting this wrong costs time either way: assuming probate is needed when it isn't means an unnecessary £526 application fee and a wait for a grant that turned out not to be required; assuming it isn't needed when a bank in fact requires one leaves that account frozen until the grant is produced. The right answer is genuinely estate-specific — what's owned, how it's owned, and each institution's own line — never one figure that applies everywhere.

Wanting a single yes-or-no answer early on is reasonable, and it can feel frustrating that the honest one depends on details you may not have gathered yet. Most executors start exactly there, not knowing — that's the ordinary starting point, not a sign of being behind.

Scotland · Northern Ireland

Scotland's equivalent to probate is called confirmation and runs under different rules; the £526 fee and the sole-name/joint-asset framing here are England & Wales only.

The limit

This module doesn't check any specific bank's current limit, confirm how a jointly-owned home is actually registered, or say whether a particular institution will insist on a grant regardless of value — some do, on their own terms. Those answers come from the institution itself, or the Land Registry, not from a general guide.

In a prepared kit

Your Kit does not decide this for you. It records where the will is kept and, beside each major high-street bank you named, that bank's own release limit with the date it was checked — the line a sole-name balance turns on.

Whether a sole-name home needs the grant turns on how it is registered, which the Kit does not record and only the Land Registry can confirm.

Contents
08

Release limits, and small estates

A bereavement release limit is the balance below which a bank will hand over a sole-name account's funds to a bereaved executor against a death certificate alone, without waiting for a grant. There is no single figure — each institution sets and publishes its own.

Barclays draws the line at £50,000 across a deceased's sole accounts; NS&I’s published threshold is far lower — £5,000 — and it reserves the right to ask for a grant at any value. Several major banks publish no fixed figure at all, deciding each case individually instead.

Whether a specific bank releases funds before a grant is issued turns entirely on that bank's own line, not any statutory rule — which is why the same estate can clear one bank instantly and freeze at another. Above a bank’s published limit it will usually require a grant of probate or letters of administration before releasing; where no fixed limit is published, the bank decides what evidence it requires for that estate.

Below a published limit, a death certificate and its own declaration form are usually enough.

It can feel arbitrary that one bank asks for a grant on a balance where another wouldn't — that reaction is fair, because the limits genuinely are set independently, institution by institution, rather than by one shared rule everyone follows the same way.

Scotland · Northern Ireland

Barclays and NS&I both state their published figures apply UK-wide, covering Scotland's grant of confirmation alongside probate and letters of administration — only the name of the court document differs there, not the amount.

The limit

Limits move, and several banks reserve the right to ask for a grant below their own published figure regardless. This module doesn't confirm today's figure for a bank not named here, or predict what any bank will actually do on the day for a particular balance — only that bank's own bereavement team can.

In a prepared kit

Where you've named a major high-street bank in your Kit, its financial picture prints that bank's own published limit beneath it — or its stated position where it publishes none — with the date checked, so you can see which of those banks need the grant and which don't. A bank the Kit holds no read position for prints nothing beneath it, rather than a guess.

Contents
09

Pensions and life insurance after a death

Most pensions pay under a nomination — also called an expression of wish — because the money sits in the scheme's own trust or contract rules, outside your estate, so your will has no authority over it. Many employers add a death-in-service benefit on the same mechanism: many schemes pay two to four times salary, guided by its own nomination, often a separate form from the pension's.

Personal life insurance sits alongside both — the same species of benefit, held and paid independently of an employer scheme.

Where the scheme has discretion, the nomination guides the decision-maker but does not bind them — never assume either result. A nomination goes stale easily: divorce changes what a will does but not, reliably, a pension nomination, and the same applies after a new partner, a birth, or a job change.

From 6 April 2027 most unused pension funds and death benefits are due to be brought within the estate for inheritance tax — though a death-in-service payment — one paid because the person was still working for that employer when they died — is excluded from that change; a lump sum from a previous job's scheme is not.

It's easy to assume a will covers everything, then learn a pension or a death-in-service payment is going by a form signed years ago and half-forgotten. Realising a nomination needs updating — after a divorce, a new partner, a new job — is an ordinary, fixable gap, not a failure.

The limit

This module doesn't say who to nominate, doesn't check any nomination actually on file, and doesn't cover pension or life-insurance tax planning — those sit with each provider and a qualified financial adviser. It states general mechanics only: what usually happens under a scheme's own rules, not what a particular scheme or policy will do.

In a prepared kit

The Kit's financial picture lists every pension provider and insurer this household named, alongside its banks, with space to mark the date each was told — so the family knows who must be contacted separately. It doesn't record nomination status; that stays with each provider.

Contents
10

What happens to the home

How a home is owned decides whether a death touches it at all. Joint tenants hold as a single unit: on a death the deceased's interest passes automatically to the surviving owner by survivorship, no grant needed for the property itself, and no executor involvement.

Tenants in common each hold a defined share instead — often 50%, sometimes not — and that share passes under the will or intestacy as part of the estate. A property registered in one name alone always falls into the estate.

The surviving co-owner does not automatically inherit a tenants-in-common share, however long a couple lived together — and a cohabiting partner who isn't married or in a civil partnership has no automatic right to the home under intestacy. Where the home is registered, the title register may carry a Form A restriction pointing to tenants in common — absence usually suggests joint tenants, but the underlying ownership documents can still matter.

Selling afterwards needs both the executor and any co-owner to act, so an early answer avoids a later stall.

Assuming shared ownership meant automatic inheritance, then discovering it didn't, can feel like the ground shifting under an already hard week. It's a common and understandable misreading of how co-ownership works, not a sign anything was arranged wrong — and confirming which type applies is usually a short, factual check.

Scotland · Northern Ireland

Scotland's equivalent process is called confirmation, not probate, and runs under its own different rules — this page's England & Wales rules do not apply there.

The limit

This module doesn't check any actual title register, doesn't identify which type of ownership applies to a specific property, and doesn't cover Scotland's different land law. A dispute between co-owners, an unregistered property, or a deed of trust overriding the register needs a solicitor's advice, not this page.

In a prepared kit

The Kit does not record how a property is owned or check the title register — that sits outside its parts. It records where the will is kept and whether one exists, which is what decides where a sole-name or tenants-in-common share goes once ownership is confirmed elsewhere.

Contents
11

Inheritance Tax and its clocks

Inheritance Tax is charged at 40% on an estate above its tax-free allowances — a £325,000 nil-rate band for everyone, plus a £175,000 residence nil-rate band when a home passes to children or grandchildren. A married couple or civil partners can transfer an unused nil-rate band to the survivor — potentially taking that band alone to £650,000 — and unused residence nil-rate band can transfer too, where its conditions are met.

Roughly 4.7% of UK estates actually pay it; property values rising against a frozen threshold mean that share grows most years.

Two clocks run at once, measured differently: form IHT400 must normally be delivered within twelve months of the end of the month in which the death occurred, while interest on any unpaid tax starts earlier — six months after the end of that month. Tax due is usually paid or arranged before probate is granted, so the six-month point matters while a family is still gathering the estate.

Miss it and interest starts automatically on the unpaid amount — 7.75% a year as of January 2026 — running daily until settled. Avoiding it starts with an IHT reference number (about three weeks' lead time), then the account itself, then roughly 20 working days for HMRC's letter — each clock able to overlap the last.

A tax bill appearing before probate is granted, mid-way through an already difficult year, can feel unfair — more so as frozen thresholds now reach estates that wouldn't have owed anything a decade ago. Most families still owe nothing; checking early replaces uncertainty with an actual number.

The limit

This module doesn't calculate anyone's actual bill, doesn't cover reliefs for business or agricultural property, trusts, or gifts, and doesn't reach Scotland or Northern Ireland's own procedural differences. It states general England & Wales rules only — a solicitor or chartered tax adviser should check any real estate before money moves.

In a prepared kit

The Kit's clock names the point interest starts on any unpaid tax — six months after the end of the month of death — keyed to this household's own date. It doesn't calculate whether tax is due or how much; that figure needs the estate's own numbers.

IV

Support, debts, and where the kit fits

The money support that exists, the debts an executor must not pay in the wrong order, and what a prepared kit already answers.

Contents
12

Bereavement benefits and money support

Several UK benefits and reliefs exist specifically for someone recently bereaved — beyond the everyday ones people already know. Bereavement Support Payment offers a lump sum plus up to 18 monthly instalments to a surviving husband, wife or civil partner — or a cohabiting partner with dependent children — but only if claimed in time: in full within 3 months of the death, at reduced value up to 12 months, and usually not at all after 21 months.

Others include a council tax exemption while a property stands empty, a temporary Universal Credit continuation, and a new leave entitlement for bereaved partners.

These schemes are easy to miss because nobody sends a letter — the household has to know to ask, and several have hard deadlines that don't extend for grief. Bereavement Support Payment stops paying its full rate after 3 months and usually closes at 21 months; the Funeral Expenses Payment has its own window.

Missing a deadline by a matter of weeks can mean losing money the household was entitled to.

Filling in benefit forms so soon after a death can feel transactional, even intrusive, at a time that feels anything but administrative. That reaction is ordinary. The forms exist because the money is real and the deadlines are real too — not because anyone expects grief to be tidy.

The limit

This module does not calculate what any individual is owed, submit a claim, or track a live deadline. Rates, caps, and the schemes on offer change; only gov.uk, DWP, HMRC, or the local council can confirm current entitlement.

It does not cover every relief that might apply to a specific household's circumstances.

In a prepared kit

No part of the Kit calculates benefit eligibility or files a claim — that stays gov.uk and DWP's own process. What the Kit does provide is a calm, dated record of the household's affairs to refer to when a claim form asks for them.

Contents
13

Debts, creditors, and protecting the executor

When someone dies, their debts become debts of the estate, not of the family. A spouse, child, or sibling is not personally liable for a sole debt unless they co-signed, guaranteed it, or held the account jointly — creditors must claim against the estate.

The executor must pay the estate’s expenses and debts in the proper legal order before distributing to beneficiaries, and can place a Section 27 notice in The Gazette to protect themselves personally: it opens a fixed window, at least two months, for unknown creditors to come forward before distribution.

An executor who pays out to beneficiaries and is then found by a genuine creditor can be made to pay that debt personally, from their own money — the estate no longer has it to give. A Section 27 notice converts that open-ended risk into a fixed wait: after the notice period expires, a personal representative who has complied with the procedure can distribute without personal liability to creditors they had no notice of, within the statutory limits.

It costs £115.86 and is optional, not compulsory.

Discovering unexpected debts, or worrying that unknown ones exist, can feel like the estate is turning against you rather than being something you administer calmly. That unease is common among executors — the notice exists precisely because nobody can see every debt a person quietly held.

Scotland · Northern Ireland

Northern Ireland has an equivalent notice under the Trustee Act (NI) 1958 (the Belfast Gazette plus two newspaper advertisements, the same two-month floor); Scotland has no direct equivalent, and settled practice is a six-month wait from the date of death before distributing a solvent estate.

The limit

This module does not decide whether your estate needs a Section 27 notice, calculate whether the estate is insolvent, or place a notice on your behalf — Valoren does not place Gazette notices, and takes no fee if you do. It is not legal advice on a complicated or contested estate.

In a prepared kit

No part of the Kit places a Section 27 notice, lists the household's debts, or advises on solvency — that stays a step you take yourself, with The Gazette or a solicitor, if this estate needs it.

Contents
14

Where this kit fits

This kit is not a template filled in with a name; it is written up from the answers one household actually gave, one part at a time — who to call first, where things are kept, the legal position, the medical essentials, the financial picture, digital access, funeral wishes. Each part exists because a specific moment in the first weeks asks for exactly that information, not because a checklist demanded a seventh box.

A kit built from a household’s own facts can be far more useful in the moment it’s needed than a generic template — a stranger's name in the wrong box helps nobody. And a kit nobody has read before it is sent can carry an error straight into a family's worst week.

That is why this one is written from the household's own answers and read by a person before it goes out.

Reading a document like this about a household — your own, or one you are now holding for someone else — can feel strange before it feels useful; that is ordinary. It is a record, not a countdown; nothing in it asks anyone to act differently today than yesterday.

The limit

This kit deliberately holds no passwords and no account balances — only names and where things are kept. It grants no legal authority and gives no advice; a registered LPA or grant of probate does.

It is a snapshot, true on the date prepared, not a subscription — it drifts the way any household's facts do.

In a prepared kit

Your kit rules a line for anything left blank, for you to fill in by hand — never guessed at — and was read once by a person before it was sent: nothing certified, nothing verified against a bank or register, only written up exactly as it was given.

Reference

Five pages behind the fourteen chapters — the dated sequence, the jurisdictions that differ, and the three registries the guide itself is built from. Every row of the three registries carries its own source and check date — 160 of them, each linked to the institution's own page. The dated sequence and the jurisdiction notes are our own compilation.

A

The first year, month by month

What falls due, and when, counted from the day of the death — the statutory clocks, not a plan. Each is the rule as published; the family's own dates are what the prepared kit computes.

The first year, month by month
WhenWhat
RegistrationThe death is registered — normally within five days of the medical examiner's office confirming registration can proceed.
Tell Us OnceThe Tell Us Once reference is used — within 28 days of receiving it at registration.
CertificatesCertified copies of the death certificate are ordered at registration — £12.50 each.
Bereavement Support PaymentA claim is made within its own windows — 3 months for the full amount, up to 18 monthly instalments, and a latest claim at 21 months.
The Gazette noticeA notice is placed in The Gazette — not less than two months must pass from the date it is published before an executor may safely distribute; the fee is £115.86 including VAT.
The probate applicationThe application for the grant is made — the fee is £526, and GOV.UK's own stated expectation is usually within 12 weeks of submitting it.
Inheritance TaxAny tax due is paid — by the end of the sixth month after the month of death; HMRC charges interest on what remains unpaid after that date.
The IHT400 accountWhere one is due, the account is delivered to HMRC — within twelve months of the end of the month of death, a separate and later deadline from the tax payment above.
The executor's yearA personal representative need not distribute the estate before this point — twelve months (one year) from the date of death.
The transferable nil-rate band claimWhere a second spouse or civil partner's own estate wants to claim it, the deadline runs from their own death — within 2 years of the end of the month they died, or, if that is later, 3 months from when their personal representatives first act.
The limit

England & Wales. A date here is the rule, not this estate's date; the executor's own calendar is built from the actual date of death.

B

Scotland and Northern Ireland — where the rules differ

The fourteen chapters describe England and Wales. These are the points where the other two jurisdictions genuinely differ — the same moments, different rules.

Scotland and Northern Ireland — where the rules differ
WhereWhat
ScotlandThe death is registered — within 8 days of the death.
ScotlandConfirmation, not probate, is applied for at the sheriff court for the area where the person last lived, on an inventory of the estate (form C1).
ScotlandAn estate worth £36,000 or less is a small estate — the sheriff clerk helps prepare the application.
ScotlandThe court fee is £351 above £50,000, and £705 above £250,000.
ScotlandLegal rights and prior rights give a spouse, civil partner and children fixed shares of the estate, whatever the will says.
ScotlandTell Us Once is offered at registration, the same as in England and Wales.
Northern IrelandThe death is registered — within 5 days of the death, unless it has been referred to the coroner, when registration waits for the coroner's certificate.
Northern IrelandThe grant is issued by the Probate Office in Belfast or the District Probate Registry in Londonderry, not by HMCTS.
Northern IrelandThe personal application fee is £407, where the estate is over £10,000.
Northern IrelandBelow £20,000, a grant may not be needed at all.
Northern IrelandTell Us Once is not offered in Northern Ireland — each department is told separately.
The limit

A death with property or family in more than one jurisdiction needs a solicitor in each; this page names the differences, it does not resolve them.

C

Release limits, bank by bank

What each bank or building society says it will release without a grant — its own published figure, or its own statement that it publishes none. Read from each institution's own guidance on the date shown.

Release limits published by UK banks and building societies, read from each institution's own bereavement guidance
BankLimitHow to tell themChecked
Barclays£50,000Four official channels, all confirmed on barclays.co.uk: (1) Online — the "Notify or add documents" form, which lets documents be uploaded immediately or added later; (2) Phone — 0800 068 2238, option 1 to notify for the first time, option 2 to speak to the dedicated bereavement team about an existing case, lines open Mon–Fri 8am–5pm and Sat 9am–2pm (closed bank holidays); (3) In branch or via video call, by booking an appointment (Barclays confirms required documents in advance for video calls); (4) By post to Bereavement Service Centre, Barclays Bank PLC, PO BOX 1495, Pallion Trading Estate, Sunderland, SR5 9YB.30 August 2026Source ↗
HSBC UK£50,000 with a will (£25,000 without)Three channels, per HSBC UK's own bereavement pages: (1) Online — the bereavement portal at hsbc.co.uk/online/bereavement/, which HSBC calls “the quickest and easiest way” and which issues a reference number for uploading the death certificate/will/grant later without re-entering personal details; (2) Phone — the dedicated Bereavement Support Team on 0800 085 1992 (+44 (0)114 252 0249 from outside the UK), open Mon–Fri 08:30–18:00 and Sat 09:00–14:00; (3) In branch — via the branch finder tool.30 August 2026Source ↗
NatWestNo general figure publishedOnline form (natwest.com bereavement guide — 'Complete online form now', with document/ID upload, 'it's ok if you don't have them right now'); phone on 0800 161 5903, lines open 9am–5pm Monday to Friday excluding bank holidays (international: +44 1204 684658; Relay UK: 18001 0800 161 5903); webchat (Mon–Fri 8am–5pm per the page); in branch.30 August 2026Source ↗
Lloyds BankNo general figure publishedPreferred/fastest route per Lloyds: its own online form — "Completing our online form is the quickest way to let us know about a death.30 August 2026Source ↗
Santander UK£50,000Phone the dedicated Bereavement team on 0800 587 5870 — the live santander.co.uk bereavement page states lines are open Mon–Fri 8am–6pm, Sat 9am–2pm (closed Sunday); note Santander's own PDF guide (dated April 2020) states different, older hours of Mon–Fri 9am–5pm only, so the hours have evidently changed since — call to confirm current hours.30 August 2026Source ↗
Nationwide Building Society£50,000Phone: 0800 464 30 18 (Mon–Fri 9am–5pm, Sat 9am–12pm, closed Sundays/bank holidays) — the dedicated Bereavement Helpdesk.30 August 2026Source ↗
HalifaxNo general figure publishedHalifax's own page states: "Completing our online form is the quickest way to let us know about a death" — linked as "Tell us about a bereavement" (apply.halifax-online.co.uk/cct1/sjlab2/pega-cs-cwa/?theme=h&formId=mot001).30 August 2026Source ↗
NS&I (National Savings and Investments)£5,000NOT covered by Tell Us Once — NS&I must be notified directly.30 August 2026Source ↗
TSB BankNo general figure publishedFastest: TSB's own online bereavement form (via DocuSign — TSB confirms it does not process the data any other way; an automatic confirmation email is sent when the form is complete).6 September 2026Source ↗
Bank of Scotland£50,000Specialist Bereavement Team: 0800 056 0073 (or +44 (0)131 278 3705 from abroad), lines open 8am–8pm, seven days a week; branch visits are by appointment (call to book); or register the death online at bankofscotland.co.uk/bereavement.6 September 2026Source ↗
Royal Bank of ScotlandNo general figure publishedRBS accepts notification online (a "tell us about a bereavement" form), by webchat (Mon-Fri, 8am-5pm), by phone on 0800 161 5904 (lines open 9am-5pm Mon-Fri, excluding bank holidays; Relay UK via 18001 0800 161 5904; from outside the UK +44 (0)1204 684 659), or in branch.6 September 2026Source ↗
first direct£50,000 with a will (£25,000 without)Online notification form (firstdirect.com), or phone the Bereavement Support Team on 0113 276 6669 (UK) / +44 113 234 5678 (Channel Islands, Isle of Man, abroad), 8am-10pm Mon-Fri and 8am-7pm Sat-Sun.6 September 2026Source ↗
The Co-operative Bank£50,000Phone: 03457 212 212 for current accounts and savings accounts, or 0345 600 6000 for credit cards — both Monday to Friday 8am-6pm, Saturday and Sunday 9am-5pm (call charges apply).6 September 2026Source ↗
Virgin Money£50,000Online form (if you already have the death certificate) — up to 10 documents per submission, 25MB max file size; or phone the Bereavement Services team on 0800 0121590 (Mon–Fri 8am–6pm, Sat 8am–3pm, Sun 10am–1pm for personal banking; some account types show 0800 011 3238, Mon–Fri 9am–5pm); or in branch.6 September 2026Source ↗
Metro Bank£25,000Email the bereavement services team (reply within 3 working days), call 0203 824 4815 (Monday to Friday, 9am to 5pm), write to Metro Bank, One Southampton Row, London WC1B 5HA, or visit a store.6 September 2026Source ↗
Starling Bank£30,000Phone 020 7930 4450, available 24/7, or email help@starlingbank.com (addressed to the Bereavement Team).6 September 2026Source ↗
Monzo£25,000Online form at monzo.com/bereavements, or email bereavements@monzo.com, or phone 0800 802 1281 (+44 203 872 0620 from abroad).6 September 2026Source ↗
Revolut UKNo general figure publishedEmail only: bereavement@revolut.com.6 September 2026Source ↗
Chase UKNo general figure publishedPhone: 0800 376 3333 (UK) or +44 20 3493 0829 (from abroad).6 September 2026Source ↗
Coventry Building Society£50,000Dedicated bereavement team on 0800 587 4565, open Monday-Friday 8am-7pm and Saturday 9am-2pm (closed Sundays and bank holidays); also by branch visit, online bereavement notification form, the NIVO app (secure messaging + document upload), or by post to Oakfield House, PO Box 600, Coventry CV3 9YR.6 September 2026Source ↗
Yorkshire Building Society£50,000YBS's own bereavement page lists four notification routes: an online bereavement form; phone 0345 166 9229, staffed 9am-5pm Monday to Friday; visiting any branch in person (bring a copy of the death certificate); or writing to the Bereavement Team, Customer Service Centre, Yorkshire Building Society, Yorkshire House, Yorkshire Drive, Bradford, BD5 8LJ.6 September 2026Source ↗
Skipton Building Society£50,000 — when a close relative is the executor; much lower for anyone else.Phone the Bereavement Team on 0345 266 1209, Monday–Friday 9am–5pm; email skiptondirect-bereavementnotification@skipton.co.uk; write to Bereavement Team, Skipton Building Society, The Bailey, Skipton, North Yorkshire, BD23 1DN (also usable as "FREEPOST, SKIPTON BUILDING SOCIETY"); or visit a branch.6 September 2026Source ↗
Leeds Building Society£50,000Notify through the cross-bank Death Notification Service (no death certificate needed to notify), by phone on 03452 682 642 (Mon–Fri 8am–6pm, Sat 9am–5pm), by emailing a copy of the death certificate to customercare@leedsbuildingsociety.co.uk, or by booking a branch appointment.6 September 2026Source ↗
Ulster BankNo general figure publishedPhone the dedicated Bereavement Services Team on 0800 096 3612 (00 44 151 494 1260 from outside the UK), 9am–5pm Monday to Friday; outside those hours the site offers its "Cora" digital assistant to route to a colleague.6 September 2026Source ↗
M&S BankNo general figure publishedOnline notification form at marksandspencer.com/bereavement-support; by phone on 0345 300 6139 (all products except Savings & Investments and general insurance, lines 9am-5pm Mon-Fri excl.6 September 2026Source ↗
Tesco Bank£50,000Phone: 0345 071 6153, Monday to Friday, 8am to 6pm (Relay UK and BSL interpreter support offered for hearing/speech difficulties).6 September 2026Source ↗
Atom BankNo general figure publishedPhone 0333 399 0050 (8am–8pm, 7 days a week); email customersupport@atombank.co.uk; or the in-app chat.6 September 2026Source ↗
Zopa BankNo general figure publishedFastest route is Zopa's own free online notification form, NotifyNow (run with its bereavement partner Phillips & Cohen Associates, who then make contact to explain next steps) — this is a Zopa/Phillips & Cohen tool, not the separate cross-bank Death Notification Service (deathnotificationservice.co.uk); no evidence Zopa participates in that industry-wide DNS.6 September 2026Source ↗
Danske Bank UK£50,000Phone 0345 600 2882 (Mon-Fri 8am-6pm, Sat 9am-1pm, closed Sundays); an online notification form ("Submit details"); visiting any branch; writing to the Bereavement Support Team, Danske Bank, Killeaton House, 41 Mosside Road, Belfast BT17 9HH; and a secure online document-upload facility for certificates once notified.6 September 2026Source ↗
Bank of Ireland UK£50,000Notify online via the online bereavement form, by post to Bank of Ireland UK Bereavement Unit, PO Box 2298, BELFAST, BT1 9AP, or in person at a local branch.6 September 2026Source ↗
AIB (NI) / Allied Irish Bank GB£25,000Phone the Bereavement Support Team on 0345 646 0320, lines open 09:00–17:00 Monday–Friday (excluding bank holidays; calls may be recorded).6 September 2026Source ↗
Handelsbanken UK£20,000Three ways: (1) contact or visit the branch where the customer held their account; (2) call the Customer Connect team, available 24 hours a day — 0800 470 8000 from the UK, +44 20 7578 8247 from outside the UK — who will identify the right branch and transfer the call (or arrange a next-working-day callback if called outside branch hours); (3) complete an online bereavement notification form (deceased's name, DOB, address/postcode, branch if known, account numbers if known, notifier's own contact details).6 September 2026Source ↗
Triodos Bank UK£25,000Notify by phone on 0330 355 0355 (+44 117 973 9339 from abroad; lines open 8am–6pm Mon–Fri, 9am–6pm Thursdays), or by completing the Bereavement Notification Form (PDF) and sending it plus a copy of the Death Certificate by email to bereavements@triodosbank.co.uk or by post to Bereavement Team, Triodos Bank, Deanery Road, Bristol, BS1 5AS.6 September 2026Source ↗
Aldermore Bank£35,000Phone 0345 604 2678 (savings customers) — lines open 8am–8pm Mon–Thu, 8am–6.30pm Fri, 9am–5pm Sat, 10am–4pm Sun.6 September 2026Source ↗
Shawbrook BankNo general figure publishedFree Death Notification Service (DNS) at deathnotificationservice.co.uk, which notifies Shawbrook (and other participating firms) from one form; Shawbrook then checks for accounts across its products and gets in touch about next steps.6 September 2026Source ↗
Paragon Bank£20,000Notify by phone, email (savings@online.paragonbank.co.uk), or post (Freepost RTEX-LLUT-KKKE, Paragon, PO Box 850, Wallsend NE28 5BJ); UK-based team available 7 days a week (0800 052 2222 for accessible-format requests).6 September 2026Source ↗
Investec Bank UK (Private Bank)No general figure publishedPhone 0330 123 3655 (+44 207 597 4131 from outside the UK) to a "dedicated team of bankers"; or write/send documents to Investec Bank plc, 30 Gresham Street, London, EC2V 7QP; or email UKServicesIncomingMail@investec.co.uk.6 September 2026Source ↗
Coutts£50,000Notify via Coutts' online bereavement form (not available for non-UK addresses), by contacting your Private Banker if you're an existing client, or by calling Coutts 24 on 020 7957 2424 (Relay UK 18001 020 7957 2424; calls recorded for training/monitoring).6 September 2026Source ↗
Al Rayan BankNo general figure publishedDigital Banking secure message (joint account holders only); email bereavementteam@alrayanbank.co.uk; post to Account Services Team, AlRayan Bank, PO Box 8177, London, W1A 8DN.6 September 2026Source ↗
Cumberland Building Society£30,000Phone 01228 403141 (see the page's own "Opening Times" link for hours); an online notification form; a downloadable/printable form returned by email (bereavement.support@cumberland.co.uk), post (FREEPOST, Cumberland House, Cooper Way, Carlisle, CA3 0JF) or in branch.6 September 2026Source ↗
Principality Building Society£39,999Email bereavement@principality.co.uk, call 0330 333 4000, visit a local branch, or post to Bereavement Team, Principality Buildings, PO Box 89, Queen Street, Cardiff, CF10 1UA.6 September 2026Source ↗
West Bromwich Building Society£30,000Online form; visiting a branch (appointment recommended, bookable online or via the branch finder); phone the Specialist Support team on 0800 280 0597; or write to Specialist Support team, the West Brom, 2 Providence Place, West Bromwich B70 8AF (or FREEPOST THE WEST BROM by ordinary post).6 September 2026Source ↗
Newcastle Building Society£30,000By phone: Savings 0345 734 4345, Mortgages 0345 601 0014, Financial Advice 0345 600 4330 (all Mon–Fri 8am–6pm except Financial Advice, 9am–5pm); in person at a branch; or by post to Newcastle Building Society, 1 Cobalt Park Way, Wallsend, NE28 9EJ.6 September 2026Source ↗
Nottingham Building Society£50,000By phone on 0344 481 4444, by visiting the nearest Nottingham Building Society branch, by post (death certificate plus covering letter) to Nottingham Building Society, Nottingham House, 3 Fulforth Street, Nottingham, NG1 3DL, or by emailing general questions.6 September 2026Source ↗
Progressive Building Society£50,000Call into a local branch; write to Progressive Building Society, 33/37 Wellington Place, Belfast, BT1 6HH; or call the helpline on 0800 029 4997 (9am-5pm, Monday to Friday) to register the death with them (the page separately lists 0800 029 4998 for making a withdrawal/general bereavement contact).6 September 2026Source ↗
The Cambridge Building Society£20,000By phone on 0345 601 3344, or in person at a local branch ('store').6 September 2026Source ↗
Saffron Building Society£15,000Phone 0800 072 1100 or visit any branch; the original Death Certificate can also be sent to Head Office (Saffron House, 1A Market Street, Saffron Walden, Essex CB10 1HX).6 September 2026Source ↗
Furness Building Society£30,000 — spouse, civil partner, parent or child only; anyone else needs the grant.Phone 0800 781 4311 for bereavement-trained colleagues (the page separately lists 0800 834 312 and a general enquiries line 0800 954 0754); email bereavement@furness-bs.co.uk; or visit a branch in person.6 September 2026Source ↗
Hinckley & Rugby Building Society£15,000By phone on 0800 434 6343, Monday–Friday 9am–5pm and Saturday 9am–12pm (closed Sundays and bank holidays), or by visiting a branch or agency (private appointments also available 2pm–5pm on weekdays).6 September 2026Source ↗
Darlington Building Society£30,000By phone: Head Office 01325 366366 (choose 'Savings', then 'Existing Savings') to book a branch appointment or speak to Customer Care; by the enquiry form on the website; or by letter to Darlington Building Society, Sentinel House, Morton Road, Darlington, DL1 4PT, stating the deceased member's full name, date of death, account number(s), and the notifier's name, address and phone number.6 September 2026Source ↗
The Melton Building Society£20,000Notify by phone on 01664 414141, by emailing enquiries@mmbs.co.uk, by writing to The Melton Building Society, Mutual House, Leicester Road, Melton Mowbray, Leicestershire, LE13 0DB, or by visiting a local branch.6 September 2026Source ↗
Marsden Building Society£15,000Preferred route is the free Death Notification Service (deathnotificationservice.co.uk), which notifies multiple banks/building societies at once — Marsden will be in touch within 10 working days of receiving that notification.6 September 2026Source ↗
Tipton & Coseley Building Society£15,000Notify in branch (no appointment needed unless a private room is wanted, in which case call 0121 557 2551) or post the original death certificate/certified copy to Tipton & Coseley Building Society, 70 Owen Street, Tipton, DY4 8HG.24 September 2026Source ↗
Monmouthshire Building Society£35,000Notify by: phoning 01633 844 340; visiting a branch or agency (calling ahead is recommended so a colleague is available); writing to Monmouthshire House, John Frost Square, Newport, NP20 1PX; or emailing via the Secure Contact Form on the Contact Us page.6 September 2026Source ↗
Newbury Building SocietyNo general figure publishedBy phone on 01635 555700; via an online death notification form on the website; in branch by prior appointment (to arrange a private meeting space); or by post to Newbury Building Society, 90 Bartholomew Street, Newbury, Berkshire, RG14 5EE (do not send original documents by post).6 September 2026Source ↗
Dudley Building Society£15,000Notify by visiting a local branch, calling 01384 231414 (advisers available 9am–5pm Mon–Fri and 9am–12pm Saturday), or emailing the Society.6 September 2026Source ↗
Leek Building Society£30,000Call 0808 281 9308 (Savings) or 0800 783 0847 (Mortgages), visit a local branch, write to Leek Building Society, 50 St Edward Street, Leek, Staffordshire ST13 5DL, or use the Contact Us section of the website.6 September 2026Source ↗
Mansfield Building Society£20,000Savings: call branch colleagues on 01623 676350 or email them; Mortgages: call the Mortgage Customer Service team on 01623 676340 or email mortgages@mansfieldbs.co.uk.6 September 2026Source ↗
Market Harborough Building Society£25,000Phone 01858 412412, Monday–Friday 9.00am–5.00pm, or visit a branch (walk-in or by appointment for privacy).6 September 2026Source ↗

59 rows.

The limit

A limit is the bank's, not the law's, and it moves. On the day, the bank's bereavement team states the current one.

D

Pensions and life insurance, provider by provider

How each provider says it handles a death — the route in, what it asks for, and whether it needs to see a grant. Read from each provider's own guidance on the date shown.

How named UK pension providers and life insurers handle a death claim, read from each provider's own guidance
ProviderPension / InsurerHow to tell themGrant of probateChecked
NESTPensionOnline claims process at bereavements.nestpensions.org.uk (notify-us-of-a-death), or call the bereavements team on 0300 020 1410 (8am-6pm Monday to Friday) if you don't have all the informationNEST pays a nominated beneficiary directly. Where nobody was nominated it pays the pot to the estate, though a pot of £5,000 or under may be paid to certain relatives instead. Claims usually settle within 20 to 30 days of NEST having everything it needs.9 September 2026Source ↗
NOW: PensionsPensionPhone 0333 091 8612 to be put through to an adviser; give the full name, date of birth and National Insurance number of the person who has diedNOW: Pensions does not mention a grant of probate or letters of administration anywhere on its page — its Trustee decides who is paid, usually following any instructions the person left.9 September 2026Source ↗
AvivaPensionOnline notification form ("Fill out an online form or call us when you're ready") or phone: UK 0345 268 2194 (Mon-Fri 9am-5pm, weekends/bank holidays closed), from abroad +44 160 360 3851.Aviva's page sets no without-grant limit for a pension claim; it says the notification process may ask for the death certificate or the grant of probate if more information is needed.9 September 2026Source ↗
Legal & GeneralPensionOnline workplace/personal pension death notification form (https://www.legalandgeneral.com/forms/retirements/workplace-death-notification/); a separate DPB (Defined Benefit pension) notification form exists for Defined Benefit schemes; a separate death-notification form is for annuity and Retired Institutional customers, and redirects pension-savings customers elsewhere.Legal & General's page does not say whether a grant is needed; it decides who benefits from the pension at its own discretion, from the information and documents submitted. For an annuity L&G is already paying, it says the process can take longer if probate is required.25 September 2026Source ↗
Scottish WidowsPensionOnline form ("Tell us online") or phone 0345 601 4179 (workplace pensions, life insurance, Retirement Account, Ready-Made Pension and annuities), Monday to Friday 9am-5pm; separate numbers for personal pensions (0345 716 6764) and older personal pensions from Lloyds TSB (0345 300 4455).Scottish Widows replies within five working days of being told, and can advance up to £10,000 to a funeral director while probate is pending. If Lloyds Bank, Halifax or Bank of Scotland has already been told, it does not need telling separately.9 September 2026Source ↗
Standard LifePensionOnline Bereavement Form at /help/bereavement/bereavement-form, or by phone/in writing per the Contact Us pageStandard Life's page does not say whether a grant is needed; pension death benefits are paid to nominated beneficiaries at the scheme's own discretion, normally outside the estate.9 September 2026Source ↗
AegonPensionBy phone, email or by writing to Aegon; the page directs the customer to search by policy number or product to get the correct team's contact details.Aegon's page does not say whether a grant of probate is needed, and says it cannot give a claim timeframe because each case is reviewed individually.10 September 2026Source ↗
Royal LondonPensionFill in the online 'Tell us someone has died' form, or call the phone line for the specific policy type (numbers vary by product, e.g.Royal London's page does not say whether a grant of probate is needed; which claims route applies depends on which Royal London product was held.10 September 2026Source ↗
M&G / PrudentialPensionOnline bereavement notification form (about 10 minutes to complete; some products are not suitable for it), or by writing to Prudential, Lancing, BN15 8GB.M&G / Prudential takes the notification through its online form or by post to its Lancing address; its page does not say whether a grant of probate is needed.10 September 2026Source ↗
Fidelity InternationalPensionNotify online via the bereavement portal (create a login), by phone 0800 41 41 16, or by post to Fidelity International, PO Box 391, Tadworth, KT20 9FU; send an original or certified death certificate.For the pension, Fidelity's pension trustees decide who benefits and write for what they need; it is not paid through the estate. Other Fidelity holdings usually need the grant, except below £50,000 where the estate is under the nil-rate band and there is a will.10 September 2026Source ↗
Hargreaves LansdownPensionContact HL's bereavement team by phone (0117 906 7806, Mon-Fri 8am-5pm) to notify them of the death; the account is then frozen pending instructions.HL does not require a grant of probate to release an HL pension at all — pension assets sit outside the estate. Its £50,000 Small Estates route applies only to HL's non-pension assets.10 September 2026Source ↗
AJ BellPensionContact the AJ Bell Bereavement Team by phone (0161 605 0326) or email (dbt@ajbell.co.uk); post the original death certificate or a certified copy (a solicitor, accountant or financial adviser can certify it) to AJ Bell, 4 Exchange Quay, Salford Quays, Manchester, M5 3EE.AJ Bell's page does not say whether a grant of probate is needed; as scheme administrator it decides how the SIPP passes on, usually following any nomination on file.10 September 2026Source ↗
Smart PensionPensionTelephone 0333 666 2626 or email; next of kin, personal representative or employer should contact as soon as possibleSmart Pension asks for the grant of probate ‘if available’ but does not say it is required; its trustees decide beneficiaries at their own discretion either way.10 September 2026Source ↗
Phoenix LifePensionOnline 'Notify us of a death' form at phoenixlife.co.uk/customer-centre/contact-us/death-claim-notification, which first asks which legacy provider (e.g.Phoenix Life's guide says a grant of probate or confirmation of the estate may be needed ‘if relevant’, not that one always is; which team handles the claim depends on which legacy provider the policy originally sat with.10 September 2026Source ↗
ReAssurePensionOnline bereavement form (easiest way), or phone/letter: former Barclays Life policies 0800 197 5616, all other policies 0800 073 1777ReAssure can release up to £10,000 straight to a funeral director before probate is resolved; the page does not otherwise say a grant is needed to pay the claim itself.10 September 2026Source ↗
NHS PensionsPensionContact NHS Pensions directly if the deceased was not actively employed; if they were still working, notify their NHS employer instead; Tell Us Once also covers notification and means no separate contact is needed.NHS Pensions does not say a grant is always needed; it says it will contact the claimant if it needs to see documents relating to probate before paying the lump sum.10 September 2026Source ↗
Teachers' PensionsPensionCall the contact centre on 0345 606 6166 (8.30am-6pm Mon-Fri) to be sent an application for death benefits, or download and post the 'Death notification and application for death benefits' form.Teachers' Pensions does not say probate is always required, but warns a claim ‘may need’ it, which can take time to arrange; it does not use Tell Us Once, so it must be contacted directly.10 September 2026Source ↗
Civil Service Pension SchemePensionComplete the online bereavement notification form, use the online contact form, or call the bereavement team on 0300 123 6666.Civil Service pensions does not say probate is required to claim, but names probate delays as one reason a case can take longer than its usual four to eight weeks.10 September 2026Source ↗
Local Government Pension Scheme (LGPS)PensionContact your (the deceased's) local pension fund directly — the LGPS is run locally by individual pension funds, not centrally, and pages direct members/dependants to their own fund for a death grant estimate or claim.The Local Government Pension Scheme does not say whether a grant of probate is needed; a death grant and any survivor's pension are paid by the local pension fund under scheme rules, not through the estate.10 September 2026Source ↗
Armed Forces Pension Scheme (Veterans UK / Ministry of Defence)PensionTell the paying agent (Equiniti) first, so the pension stops; then contact the Armed Forces Pension Schemes Team (Veterans UK, Glasgow) to claim any dependant's pension.Tell the paying agent first, so the pension stops; a dependant claims any dependant's pension from the scheme team. Only a lump sum with no eligible dependant becomes part of the estate.10 September 2026Source ↗
State Pension (DWP / The Pension Service)PensionTell Us Once service (or notify DWP/HMRC directly if Tell Us Once cannot be used); then contact the Pension Service directly to claim any extra payment based on the deceased's National Insurance contributions.The State Pension is not a lump sum paid to the estate; a surviving spouse or civil partner over State Pension age may inherit or claim extra, based on the deceased's own National Insurance record.10 September 2026Source ↗
AvivaInsurerOnline notification form or phone call; Aviva asks for the deceased's full name, date of birth, address (policy number helpful but not required), and the notifier's own details and relationship to the deceased.Aviva's page sets no without-grant limit for a life claim; it says it may ask for the death certificate or the grant of probate as part of the notification process.10 September 2026Source ↗
Legal & GeneralInsurerStart a claim online: joint policy via online account login; single Life Insurance or Over 50 Life Insurance policy via the Claims Portal.If the policy is in trust, L&G pays the trustees, who can usually claim without waiting for probate; for a policy not in trust, the page does not say whether a grant is needed.10 September 2026Source ↗
Scottish WidowsInsurerOnline form (fastest route), phone 0345 601 4179 (Mon-Fri 9am-5pm, closed weekends/bank holidays), or write in.Scottish Widows replies within five working days of being told, and can advance up to £10,000 to a funeral director while probate is pending. If Lloyds Bank, Halifax or Bank of Scotland has already been told, it does not need telling separately.10 September 2026Source ↗
Royal LondonInsurerOnline form ("Tell us someone has died") or phone, with the exact number/route depending on policy type (e.g.Royal London's page does not say whether a grant is needed; which claims route applies depends on which type of policy was held.10 September 2026Source ↗
LV=InsurerOnline form directly to LV=, or via the Life Ledger third-party bereavement-notification platform (partnered service).LV= says probate is not always required to make a claim, and what it asks for can vary by the type of policy held.10 September 2026Source ↗
SunLifeInsurerCall 0800 008 6060 (Mon-Fri 8am-8pm), or post documents to SunLife, PO Box 1395, Peterborough, PE2 2TR, United Kingdom.SunLife's page does not say whether a grant of probate is needed for a claim.10 September 2026Source ↗
Phoenix LifeInsurerhttps://www.phoenixlife.co.uk/customer-centre/contact-us/death-claim-notification (Notify us of a death — provider-selection tool, since Phoenix Life absorbed dozens of legacy insurers)Phoenix Life says a grant of probate may be needed ‘if relevant’; a policy held in trust is paid directly to the beneficiaries, outside the estate. Which team handles the claim depends on which legacy provider the policy originally sat with.10 September 2026Source ↗
ReAssureInsurerOnline bereavement notification form (linked from the making-a-claim page), or by phone/letter to the Bereavement TeamReAssure can release up to £10,000 straight to a funeral director before probate is resolved; the page does not otherwise say a grant is needed to pay the claim itself.10 September 2026Source ↗
Canada LifeInsurerOnline bereavement notification form, or by phoneCanada Life's page does not mention a grant of probate as a requirement; it asks for a death certificate and a copy of the will to process a beneficiary claim.10 September 2026Source ↗
AegonInsurerRegister the death at the local Register Office first, then formally notify Aegon; original death certificate to be sent by post.Aegon's general bereavement glossary says a grant may be needed to administer an estate, ‘depending on the value’, but its pages do not say whether Aegon itself requires one to pay a protection claim.10 September 2026Source ↗
Prudential (M&G)InsurerOnline bereavement notification form (mypru.pru.co.uk/onlinebereavement/intro, ~10 minutes), or by post to Prudential, Lancing, BN15 8GB.Prudential takes the notification through its online form or by post to its Lancing address; its page does not say whether a grant is needed to pay a life claim.10 September 2026Source ↗
The People's PensionPensionThrough the Contact us page, which offers a 'Contact our bereavement team' option (an enquiry form).The People's Pension does not say whether a grant is needed; its Trustee pays the pot at its discretion, guided by any expression of wish on record, outside the estate. It puts no timescale on a death claim — each is looked at individually.10 September 2026Source ↗
VitalityInsurerCall the life claims team on 0345 601 0072 or email lifeclaims@vitality.co.uk, Monday to Friday 8.30am to 5pm.Vitality's page does not say whether a grant is needed; a VitalityLife plan pays out to the owner's estate unless trustees or beneficiaries were nominated. A claim starts by phone or email with the life claims team.10 September 2026Source ↗
ZurichInsurerThe online claims form, in two versions by policy number: policies starting PR (0370 240 0073, zurichmulticlaims@uk.zurich.com) and all other policies (0370 243 0827, bereavements.zurich@uk.zurich.com), 9am to 5pm Monday to Friday; 0370 333 1500 if the policy number is not known.Zurich's page does not say whether a grant is needed; it asks for the policy number, the original death certificate or coroner's interim report, and details of the estate. A policy held in trust is paid in line with the trust; otherwise to the relevant beneficiaries.10 September 2026Source ↗

35 rows.

The limit

A provider's process is its own and moves; a policy written in trust and a pension paid at the trustees' discretion sit outside the estate, and each provider's bereavement team states its current position.

E

Who else must be told — the directory

Every organisation a household commonly has to tell, with the route each one publishes — read from its own page on the date shown.

Organisations a household commonly has to tell after a death, with the route each one publishes
OrganisationSectorThe route inPhoneChecked
Tell Us OnceGovernmentSet up by the registrar when you register the death — they either complete it with you or give you a unique reference number to use online or by phone.The registrar gives you the number to call (Relay UK available; a BSL video relay service exists)20 August 2026Source ↗
Death Notification ServiceMulti-institution serviceOne free online submission notifies every member bank and building society at the same time.—20 August 2026Source ↗
BarclaysBankOnline notification form (their stated first route — no call or visit needed), or phone, branch, or post.0800 068 2238, then option 2 for the bereavement team20 August 2026Source ↗
HSBC UKBankOnline "Share bereavement details" portal, available 24 hours a day — their stated quickest route.0800 085 1992 (+44 (0)114 252 0249 from outside the UK)2 September 2026Source ↗
Lloyds BankBankOnline bereavement form — their stated quickest route.0800 015 0012 (+44 (0)1733 261630 from abroad)20 August 2026Source ↗
HalifaxBankOnline bereavement form — their stated quickest route.0800 015 0012 (+44 (0)1733 261630 from abroad)20 August 2026Source ↗
NatWestBankOnline form — their stated fastest route.0800 161 5903 (Relay UK: 18001 0800 161 5903)20 August 2026Source ↗
Santander UKBankOnline form, phone, branch or post — four published routes.0800 587 587020 August 2026Source ↗
Nationwide Building SocietyBuilding societyOnline form (via DocuSign) — their stated first step.0800 464 30 1820 August 2026Source ↗
TSBBankOnline form — their stated fastest route, but photo ID is mandatory to complete it.0345 835 783424 September 2026Source ↗
MonzoBankOnline form at monzo.com/bereavements, or email.—20 August 2026Source ↗
Starling BankBankPhone or email, 24 hours a day, seven days a week — documents follow by email or post.020 7930 445020 August 2026Source ↗
AvivaInsurerOnline notification form, or phone if you would rather give the details by voice.0345 268 219420 August 2026Source ↗
Legal & GeneralInsurerIt depends on the product.0800 137 101 (life insurance bereavement claims) · 0800 009 3506 (Over 50s life insurance claims) · 0345 026 3858 (retirement income and annuities) · 0345 678 0020 (personal pensions with a policy starting 'S', ISAs and investments)24 September 2026Source ↗
BTTelecomsOnline form, or phone — the widest published hours of any entry here.0800 169 166320 August 2026Source ↗
DVLAGovernmentTell Us Once covers the driving licence and vehicle tax — but vehicles and personalised registrations still need telling separately.Contact DVLA through the help route on the page20 August 2026Source ↗
Chase UKBankPhone, post or email direct to Chase's own Bereavement Team; Chase also promotes the multi-bank Death Notification Service (DNS) online form first for people notifying several banks at once, which skips the death-certificate copy and ID checks and gets a reply within 10 working days.0800 376 3333 (from the UK) / +44 20 3493 0829 (from abroad)31 August 2026Source ↗
first directBankOnline form is first direct's own stated quickest way to notify them; a phone line (8am–10pm weekdays, shorter at weekends), any HSBC branch in person, post, or the multi-bank Death Notification Service are also offered.0113 276 6669 (UK) / +44 113 234 5678 (Channel Islands, Isle of Man and abroad)31 August 2026Source ↗
Metro BankBankEmail, phone, post, or visiting any Metro Bank store — Metro Bank present all four as equal options with none called out as quickest; email replies come within 3 working days, and only one notification to Metro Bank is needed to find all of the person's accounts with them.0203 824 481531 August 2026Source ↗
Revolut UKBankEmail only, to bereavement@revolut.com — Revolut don't take bereavement notifications by phone, post or online form.—31 August 2026Source ↗
The Co-operative BankBankThe Co-operative Bank's own stated easiest way is their NIVO mobile app, for uploading documents and messaging the bereavement team; an online bereavement instruction form, phone, or an in-branch appointment are also offered.03457 212 212 (current and savings accounts) / 0345 600 6000 (credit cards)31 August 2026Source ↗
Virgin MoneyBankPhone is the personal-banking bereavement team's primary route; an online upload form is offered as an alternative once you already have the death certificate.0800 0121590 (personal banking accounts not originally opened with Clydesdale or Yorkshire Bank) / 0800 011 3238 (accounts originally opened with Clydesdale or Yorkshire Bank) / 0800 756 0800 (business accounts)3 September 2026Source ↗
Leeds Building SocietyBuilding societyUse the Death Notification Service, or contact Leeds directly by phone, email, or a branch appointment — no death certificate is needed to make the initial notification.03452 682 64231 August 2026Source ↗
Skipton Building SocietyBuilding societyCall or email the Bereavement team to notify them, or print and complete the Bereavement Notification Information Request Form and drop it off at your nearest branch or post it — for savings balances under £5,000, or for mortgage accounts, they may accept a scanned document by email instead of the original.0345 266 120931 August 2026Source ↗
Yorkshire Building SocietyBuilding societyUse their online bereavement form, or call the team on 0345 166 9229 — you can also visit a branch or write in.0345 166 922931 August 2026Source ↗
M&G / PrudentialInsurerUse the online bereavement notification tool — usually around 10 minutes to complete — or write to their Lancing address; the page publishes no working phone number (see notes).—31 August 2026Source ↗
Standard LifeInsurerFill in the online bereavement form — Standard Life's stated easiest way to tell them a customer has died.—31 August 2026Source ↗
SunLifeInsurerCall SunLife's UK claims line to start a death claim, or write to their Peterborough PO Box — no online claim form or email is published for insurance bereavement claims on this page.0800 008 606031 August 2026Source ↗
Nest PensionsPension providerNotify Nest online through their bereavement portal — the quickest way to get started — or call their bereavements team; claims are usually settled within 20–30 days of Nest receiving all the information needed.0300 020 141031 August 2026Source ↗
giffgaffTelecomsEmail the bereavement team, or start a live chat request via the help page — either can close or keep the account, as you choose.—31 August 2026Source ↗
O2TelecomsChoose 'Disconnect' or 'Transfer responsibility' on O2's bereavement page, or contact the Bereavement and Critical Illness team by phone, email or post.0800 090 18 2031 August 2026Source ↗
PlusnetTelecomsPhone Plusnet directly to cancel or transfer the account — no online form.0330 1239 12331 August 2026Source ↗
TalkTalkTelecomsPhone the dedicated bereavement team — no online form is offered.0345 172 003831 August 2026Source ↗
Three UKTelecomsOnline bereavement form, or call the bereavement team directly.0333 338 140031 August 2026Source ↗
Virgin MediaTelecomsDownload and submit the Bereavement Transfer form or the Bereavement Disconnect form, or call the bereavement line.0800 952 230231 August 2026Source ↗
Vodafone UKTelecomsCall the dedicated bereavement team for free, or complete the online bereavement form — either closes the account, transfers it, moves it to Pay As You Go, or moves it to another network.0808 005 745024 September 2026Source ↗
E.ON NextEnergyE.ON Next's own online form is described as "the simplest way to get in touch" and you don't need to be the legal executor to use it — or call/email their bereavements team directly.0808 501 503531 August 2026Source ↗
Octopus EnergyEnergyOctopus's own stated route is Settld's free online form (Octopus pays for the service, Settld notifies them and handles the process) — or contact Octopus directly with the same details if you'd rather not use Settld.—31 August 2026Source ↗
OVO EnergyEnergyFill out OVO's online bereavement form on their "What to do if the account holder passes away" page, or call/email their dedicated team directly.0330 175 968331 August 2026Source ↗
Scottish PowerEnergyCall Scottish Power's bereavement team, or complete their bereavement notification form and email it in.0800 074 198631 August 2026Source ↗
Utility WarehouseEnergyCall Utility Warehouse's Bereavement Support team, or complete their bereavement form and email it back with any supporting documents.0333 005 835631 August 2026Source ↗
Anglian WaterWaterPhone their bereavement line on 0800 141 2944, use live chat, complete their online form (offered explicitly as an alternative for anyone who'd rather not call), or write to them.0800 141 294431 August 2026Source ↗
Severn TrentWaterComplete their online form, message their WhatsApp virtual assistant, or call 0345 7500 500 (Mon–Fri, 9am–5pm) — these are Severn Trent's own channels; they also point to the third-party service Life Ledger.0345 7500 50031 August 2026Source ↗
Southern WaterWaterComplete one of their online forms — change the account name, add executor's details, or close the account — with phone support on 0330 303 0368 if you need help filling them in.0330 303 036831 August 2026Source ↗
Thames WaterWaterOnline form is their stated simplest way to notify them, or phone 0800 009 4976 (Mon–Fri, 9am–5pm) — a recorded message may suggest using the website instead, but Thames Water ask callers to stay on the line to reach a team member.0800 009 497631 August 2026Source ↗
United UtilitiesWaterComplete their online form (their stated primary route), or call 0800 912 7249 — no phone hours are published.0800 912 724931 August 2026Source ↗
Yorkshire WaterWaterPhone 0345 1 24 24 24 or request a callback — Yorkshire Water say this is 'the best way' to tell them; there is no dedicated online bereavement form.0345 1 24 24 2431 August 2026Source ↗
Amazon UKDigital & online accountsEmail bereavement-support@amazon.co.uk — Amazon's bereavement team is the single point of contact.—31 August 2026Source ↗
AppleDigital & online accountsIf you're a named Legacy Contact, start a request on Apple's Digital Legacy site using your access key and the death certificate.—31 August 2026Source ↗
Facebook / MetaDigital & online accountsSubmit Meta's Special Request form online and choose whether to memorialise or remove the account — memorialisation needs an obituary, death certificate or memorial card; removal needs a death certificate.—31 August 2026Source ↗
GoogleDigital & online accountsUse Google's online troubleshooter to choose one of the request types — closing the account, or requesting funds or content from it — Google reviews each request individually before deciding.—31 August 2026Source ↗
MicrosoftDigital & online accountsIf you know the account's sign-in details, sign in and close the account yourself.—24 September 2026Source ↗
NetflixDigital & online accountsIf you have the account's sign-in details, cancel it yourself from the Account page.—31 August 2026Source ↗
PayPal UKDigital & online accountsEmail bereavement@paypal.co.uk (or write to PayPal's London office) with a cover sheet, the death certificate, and details to locate the account — PayPal reviews the documents and then closes or locks the account.—31 August 2026Source ↗
Royal MailPostRedirecting a deceased person's mail is a separate 'Special Circumstances' service from Royal Mail's standard paid house-move redirection, and cannot be set up online — you apply at a Post Office branch or by post, showing documentation of your authority to act.—24 September 2026Source ↗
Experian UKCredit fileAn executor or administrator sends Experian a copy of the Grant of Probate or Letters of Administration, proof of their own identity, and proof of their own address by post — ideally via a Statutory Credit Report application — to have the deceased's file marked and released.—1 September 2026Source ↗
British GasEnergyBritish Gas's own probate and bereavement page runs a 'How to let us know' flow, and states you don't need everything ready to start it — or call the dedicated team.0330 808 38801 September 2026Source ↗
EDFEnergyEmail or call EDF's energy specialists.03330 069 95017 September 2026Source ↗
TV LicensingLicenceTwo routes, and TV Licensing asks you to pick: transfer the licence to someone else at the same address, or cancel it and apply for a refund.0300 131 12611 September 2026Source ↗
SkyTelecomsSky's own bereavement article offers chat or phone through its 'Get in touch' panel, and says it can either change ownership of the Sky account to next of kin or partner, or cancel it completely.—1 September 2026Source ↗
EETelecomsOne online form.—1 September 2026Source ↗
Tesco BankBankPhone their Estates team, or write to them freepost.0345 071 615317 September 2026Source ↗
Coventry Building SocietyBuilding societyThree ways in: their online form, the NIVO secure messaging app, or a call to the dedicated bereavement team.0800 587 4565 (dedicated bereavement team)17 September 2026Source ↗
AXAInsurerPhone the line for the policy type.Car 0330 024 1158 · Home 0330 024 1235 · Van 0330 159 1509 · Landlord 0330 159 1512 · Business 0330 159 150817 September 2026Source ↗
AdmiralInsurerPhone, live chat or post.0333 234 997117 September 2026Source ↗
Scottish WidowsPension providerOnline form is the quickest.0345 601 4179 (workplace pensions, life insurance, Retirement Account, Ready-Made Pension, annuities) · 0345 716 6764 (personal pensions) · 0345 300 4455 (older personal pensions from Lloyds TSB) · 0345 300 2540 (savings and investments — OEICs, ISAs, bonds)17 September 2026Source ↗

66 rows.

The limit

Sixty-one is not everyone. An organisation missing here has not been read, not ruled out.

Take the whole thing with you

The same fourteen chapters, as a 33-page PDF you can print or forward — with every figure's source and checked date on its last pages. It is the edition that travels with a prepared kit, and it is the same document either way — nothing is held back for buyers.

Download the PDF →

September 2026 edition

This guide is general, and the same for every household. What it cannot do is answer for this family — which bank, which pension, whose name is on the deeds, who to call first.

The Family Handover Kit is that part: the place those answers are written down — and, for each one you do not have yet, where to look, from the National Will Register to the Pension Tracing Service. Nothing is asked of you first; twenty-four optional questions come with it, and the edition they produce is written up from your answers and read through by a person before it is sent.

The reference work behind it, also free

The figures in this guide are not assertions — they are read off datasets we publish in full, each row carrying its own source and the date we last checked it. All four are free to read and free to download. No account, no email.

FAQ

About this guide.

Yes. All fourteen chapters are on this page, and the same document is a free PDF download. There is no account, no email address and no purchase in the way. It is written to be useful to someone who never buys anything from us.
The family after a death. It is written to be picked up at the chapter a moment puts in front of you, not read cover to cover. If you are preparing in advance, the chapters still read as a map of what your family will meet.
The procedure described is England and Wales. Where Scotland or Northern Ireland genuinely differ, that chapter says so — confirmation instead of probate, an eight-day registration window, a separate probate office — so you are never quietly reading the wrong jurisdiction's rules. Chapters covering UK-wide matters, such as Inheritance Tax and bereavement benefits, carry no such note because there is nothing to distinguish. Appendix B collects every point of difference on one page.
Every fee, threshold and statutory window in the guide is anchored to a watched register rather than typed in by hand, and re-checked on a schedule. The edition date is printed on the last page of the PDF. A guide that was accurate the day it was written and never checked again is the ordinary failure in this category.
It does not settle a particular estate. Each chapter ends with its own limit — the point where a general guide stops being useful and a specific set of facts takes over. That is the honest boundary, and it is why the limits are printed rather than buried.
The guide is general and the same for everyone; the Kit is this household's own answers, written up and read by a person before it is sent. The guide travels with a Kit rather than instead of one — each chapter says which part of a prepared kit already answers that moment.
Part of a working library79form walkthroughs90+free guidesevery calculator & checker